

Are you a medical professional looking to buy a home? You’re in the right place! At Loan Nerds, we understand the unique financial circumstances that doctors face when applying for home loans. Whether you’re a GP, specialist, or surgeon, this guide will walk you through everything you need to know about doctor home loans and the application process, helping you secure the best deal for your dream home.
What Are Doctor Home Loans?
A doctor home loan is a type of mortgage specifically designed for medical professionals. While it’s not a unique loan product that applies to all doctors, it’s a set of benefits and features that lenders often offer to healthcare professionals due to their stable, high-income careers and low-risk borrower profile.
Doctors typically enjoy advantages such as:
- The potential to avoid Lenders Mortgage Insurance (LMI), even with a deposit of less than 20%.
- Discounted interest rates compared to standard loan products.
- Streamlined approval processes that make the home loan application easier and faster.

Who Are Eligible for Special Home Loan Deals?
Medical professionals are considered low-risk borrowers by banks, making them eligible for special home loan deals. Lenders value the stability and reliability of individuals in the healthcare sector. This includes a variety of occupations, such as:
- Surgeons
- Anaesthetists
- Internal Medicine Specialists
- Psychiatrists
- General Practitioners (GPs)
- Dentists
- Pharmacists
- Veterinarians
- Optometrists
- Chiropractors
How to Apply for a Doctor Home Loan
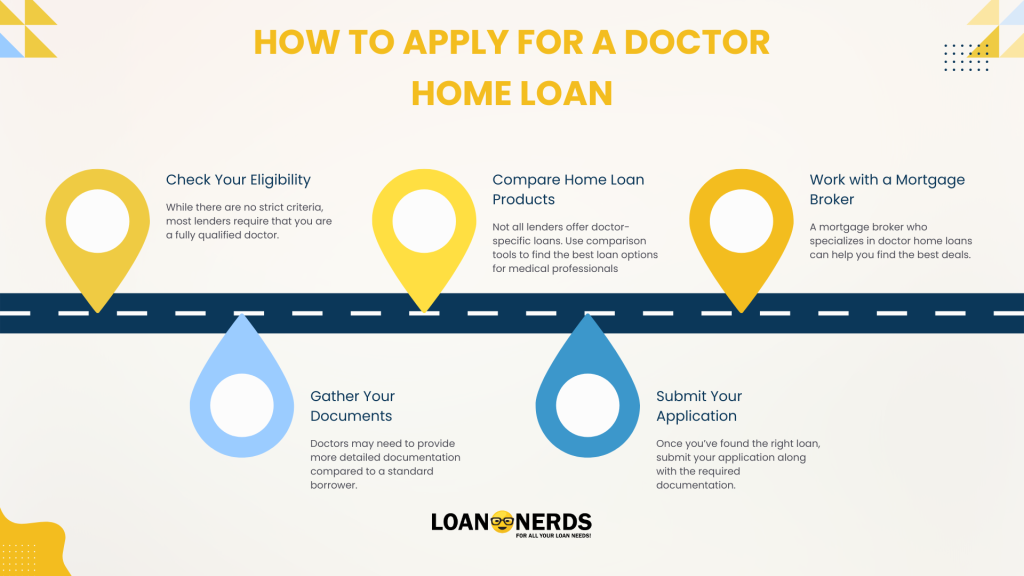
Applying for a doctor home loan is similar to applying for a standard home loan, but with a few key differences. Here’s a breakdown of the steps involved:
- Check Your Eligibility
While there are no strict criteria, most lenders require that you are a fully qualified doctor. Some lenders may also consider additional factors such as your income and employment status. If you’re self-employed, be prepared to provide extra documentation. - Gather Your Documents
Doctors may need to provide more detailed documentation compared to a standard borrower. For example, if you are self-employed or a contractor, you might need to submit:- One to two years of business tax returns
- Two years of personal tax returns
- Your most recent notice of assessment from the Australian Tax Office (ATO)
- Two years of bank and financial statements from your business
- Compare Home Loan Products
Not all lenders offer doctor-specific loans. Use comparison tools to find the best loan options for medical professionals, paying attention to features like interest rates, deposit requirements, and whether LMI is waived. - Submit Your Application
Once you’ve found the right loan, it’s time to submit your application along with the necessary documentation. The lender will review your information and assess your eligibility. At Loan Nerds, we make this process even easier.
Submit your application with us, and in under one minute, you’ll have access to over 50+ lenders, streamlining your journey to homeownership. - Work with a Mortgage Broker
A mortgage broker who specializes in doctor home loans can be invaluable in helping you navigate the application process. They’ll connect you with lenders who understand the unique financial situation of doctors and can help you find the best loan deals. By working with a broker, you can save time and ensure you’re getting a loan tailored to your specific needs.
What Are the Benefits of Doctor Home Loans?
There are several key benefits that come with applying for a doctor home loan:
- Avoid LMI
Doctors with less than a 20% deposit can often avoid paying LMI, which is typically required when borrowing more than 80% of the property’s value. By saving as little as 5%, you could secure your home loan without this additional cost. - Discounted Interest Rates
Many lenders offer doctors discounted interest rates because they are considered low-risk borrowers. These discounts can make a significant difference over the life of your loan. - Fee Waivers
In some cases, lenders may waive or reduce certain fees, such as application fees, ongoing account fees, or valuation fees. Be sure to ask your lender about any available fee waivers. - Streamlined Approval Process
With a doctor home loan, the approval process is often faster and less complicated. Lenders understand the nature of your profession and may be more flexible with your documentation requirements.
What Our Clients Say
“Loan Nerds team was amazing—very friendly and easy to work with. They made the whole process so simple and clearly explained everything, especially for someone buying their first home. I would definitely recommend them to my family and friends!”
— Dr. Asif Khattak
Is It Easy for Doctors to Get a Home Loan?
While doctors have a strong financial profile, the process of securing a home loan is not always straightforward. Self-employed doctors, in particular, may face a more complex approval process due to the need to provide additional documentation.
However, lenders are often more willing to work with medical professionals and may offer faster approval times and more flexible terms compared to standard applicants.
How Can You Find the Best Doctor Home Loan?
If you’re a doctor looking for a home loan, here’s how you can find the best deal:
- Use Online Comparison Tools
Research doctor-specific loans using comparison tools like Canstar or Finder. - Contact Lenders Directly
Speak to your lender and explain that you’re a medical professional. They may be able to offer you a better deal based on your status. - Work with a Mortgage Broker
A mortgage broker can help you navigate the doctor home loan market, ensuring you find the best loan with the best terms for your needs.
Ready to Get Started?
At Loan Nerds, we specialize in making the home loan process simple for doctors. Whether you’re buying your first home or upgrading to a bigger space, we’re here to help you secure a loan that fits your needs.
Contact us today to find out more or get started on your application!
FAQs About Doctor Home Loans
1. Can I get a doctor home loan with a small deposit?
Yes, many lenders will allow you to borrow up to 95% of the property’s value, meaning you can purchase a home with as little as a 5% deposit.
2. What documents do I need as a self-employed doctor?
Self-employed doctors will need to provide additional documentation, such as tax returns, business financial statements, and ATO notices of assessment.
3. Can doctors get discounts on interest rates?
Yes, doctors often qualify for lower interest rates due to their stable income and low-risk status.
4. How do I apply for a doctor home loan?
You can apply for a doctor home loan by comparing options online, contacting lenders directly, or working with a mortgage broker who specializes in medical professionals.
With the right guidance and support, securing a doctor home loan can be a straightforward and rewarding process. Let Loan Nerds help you every step of the way toward your homeownership goals!

