


At Loan Nerds, we understand that securing a home loan can be a challenge, especially for those with non-traditional income sources. Whether you’re self-employed, a small business owner, or have an irregular income, finding the right home loan product is crucial. That’s why we’re here to break down the key differences between Full Doc, Alt Doc, and Low Doc home loans to help you make an informed decision.
What Are Full Doc Home Loans?
A Full Doc home loan is the most common type of mortgage, especially for borrowers with a stable and consistent income. To apply for this loan, you’ll need to provide a comprehensive set of documents that lenders use to assess your ability to repay the loan. These documents generally include:
- Tax returns for the last two years
- Notice of Assessment from the ATO
- Payslips or income statements from your employer
- Bank statements showing consistent income deposits
For self-employed individuals, Full Doc loans will typically require tax returns and business financial statements. This option is ideal for those who can provide all the necessary documentation and have a reliable, salaried income. Full Doc loans tend to offer lower interest rates because they are considered less risky for lenders.
What Are Alt Doc Home Loans?
An Alt Doc (Alternative Documentation) loan is perfect for those who have non-traditional sources of income, such as self-employed borrowers. If you’re unable to provide the standard tax returns and payslips, Alt Doc loans give you more flexibility by allowing you to use alternative forms of documentation. This could include:
- Business bank statements from the last six months
- BAS (Business Activity Statements) from the last six months
- An Accountant’s Letter verifying your income and business stability
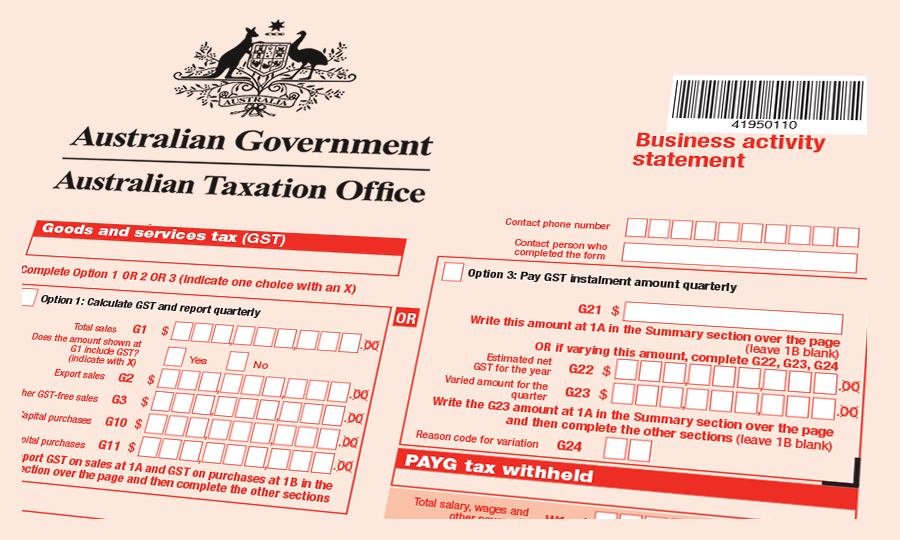
At Loan Nerds, we work with various lenders who offer Alt Doc loans tailored for self-employed individuals. These loans are perfect if your income is irregular or your financial documentation doesn’t fit the traditional mold. While Alt Doc loans may not offer the lowest rates like Full Doc loans, they are a great option for those who need more flexibility.
What Are Low Doc Home Loans?
A Low Doc (Low Documentation) loan is for borrowers who can’t provide the full range of documentation required for Full or Alt Doc loans. These loans are especially popular among individuals with highly irregular or non-traditional income sources.
To qualify for a Low Doc loan, you may only need to provide minimal documentation, such as:
- Bank statements for the last few months
- Statutory declaration or self-certification of income
However, Low Doc loans typically come with higher interest rates due to the higher risk involved for lenders. In some cases, you may also be required to take out Lender’s Mortgage Insurance (LMI) if you default on the loan.
While Low Doc loans offer fewer requirements, they are not always the best choice, as the higher rates can result in paying more in the long run. It’s important to carefully assess whether this option is right for your financial situation.
Key Differences Between Full Doc, Alt Doc, and Low Doc Loans
| Feature | Full Doc Loans | Alt Doc Loans | Low Doc Loans |
|---|---|---|---|
| Documentation | Detailed financial documents (tax returns, payslips, etc.) | Alternative forms like business statements and bank statements | Minimal documentation (bank statements, statutory declaration) |
| Income Type | Salaried, stable income | Self-employed, non-traditional income | Self-employed, irregular income |
| Eligibility | Easier for borrowers with stable income | Suitable for self-employed individuals | Ideal for those who cannot provide full documentation |
| Interest Rates | Generally lower due to lower risk | Higher than Full Doc loans | Higher due to increased risk |
Which Loan Is Right for You?
Choosing the right loan depends on your specific financial situation. Here’s a quick guide to help you decide:
- Full Doc loans are perfect if you have a stable, salaried job and can provide the required documentation.
- Alt Doc loans are great for self-employed individuals who may not have traditional tax returns but can provide alternative forms of income verification.
- Low Doc loans are for those with irregular income, but be prepared for higher interest rates and potentially more risk.
Why Choose Loan Nerds?
At Loan Nerds, we specialize in helping you find the right loan that matches your unique financial situation. Whether you’re a first-time homebuyer, self-employed, or looking to refinance, our team of expert mortgage brokers is here to guide you through every step of the process.
With access to over 50 lenders, we’re committed to finding the best loan solution for you. Our personalized service ensures that we take the time to understand your needs and match you with the loan that suits your long-term financial goals.
Contact Loan Nerds today to learn more about your home loan options, or to get started on your application. Let us help you secure the right loan and achieve your homeownership dreams!

