

A home equity loan can help Australian homeowners unlock the value in their property for renovations, investments, or other major expenses. Below, we’ll cover everything you need to know about home equity loans in Australia, including how they work, their requirements, and how you can use them effectively.
What Is Home Equity?
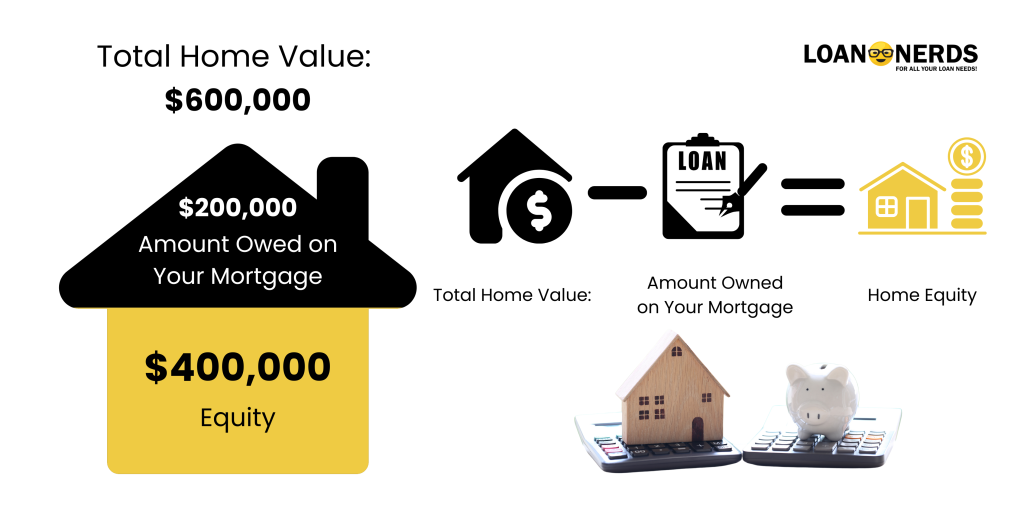
Home equity represents the portion of your property that you own outright, calculated as the difference between your home’s market value and your remaining mortgage balance. For instance, if your home is worth $600,000 and you owe $200,000 on your mortgage, you have $400,000 in equity. As property values rise or as you pay down your loan, your equity grows, increasing the amount you may be eligible to borrow.
Lenders in Australia typically allow access to up to 80% of the property’s value in the form of a home equity loan, provided you meet certain financial criteria.
How Do Home Equity Loans Work in Australia?
A home equity loan allows you to borrow against the equity in your property, using your home as collateral. Australian lenders offer several types of home equity loans to suit different needs:
1. Home Loan Top-Up
Also known as a ‘cash out’ or ‘lump sum’ loan, this is the most common type of home equity loan. With a top-up, you receive a lump sum added to your current mortgage, which you then repay over a fixed period. Each payment reduces the loan balance, making this an effective way to access funds for renovations, investments, or other major expenses.
2. Line of Credit
A line of credit provides ongoing access to funds as needed, similar to a credit card. The loan amount sits in a transactional account, and you only pay interest on what you actually withdraw. This flexible option is ideal if you want to access your equity gradually, rather than in a single lump sum.
3. Renovation Loan
Tailored specifically for home improvements, a renovation loan allows you to use your home equity to fund upgrades that can increase your property’s market value. By using a renovation loan, homeowners can enhance their property’s appeal while potentially boosting their overall equity.

4. Seniors Equity Loan
Known as a reverse mortgage, this type of loan is available to those over 60 and allows retirees to access their home’s equity without immediate repayments. Instead, interest accumulates over time, and the loan (including interest) is repaid once the property is sold. While this option offers access to funds in retirement, it carries risk and should be carefully considered with advice from a financial expert.
Requirements for Accessing Home Equity in Australia
Lenders have specific requirements for home equity loans, which may include:
- Sufficient Equity: Typically, you’ll need at least 20% equity in your property to access a home equity loan without requiring Lenders Mortgage Insurance (LMI).
- Good Credit History: A solid credit score indicates reliability and financial responsibility, which lenders value.
- Stable Income: Consistent income ensures you can meet increased repayment obligations.
- Property Valuation: Lenders usually require an updated valuation to confirm the current market value and available equity of your property.
Meeting these requirements improves your chances of securing a loan with favorable terms.
Rates and Fees for Borrowing Against Your Home Equity in Australia
Home equity loans typically offer lower interest rates than personal loans or credit cards, as the loan is secured against your property. Here’s what to consider:
- Fixed vs. Variable Rates: Fixed interest rates lock in a rate over a set term, offering predictable payments, while variable rates can fluctuate based on market changes.
- Application and Valuation Fees: Some lenders charge application and valuation fees to assess your property’s worth.
- LMI (Lenders Mortgage Insurance): LMI may apply if you’re borrowing more than 80% of your home’s value.
- Monthly/Annual Fees: Certain loan types, like lines of credit, may incur monthly or annual fees for account management.
Comparing fees and interest rates from multiple lenders can help you find the best loan to suit your financial situation.
How to Use Your Home Equity in Australia
Home equity can be used for a range of financial purposes, each with its unique benefits and risks:
- Renovations: Using equity to fund home improvements can increase your property’s value, potentially boosting your total equity.
- Investment Property: Many Australians use their equity as a deposit to buy a second property, often as a way to generate rental income or build wealth.
- Debt Consolidation: Using equity to consolidate higher-interest debt can simplify finances and reduce interest costs.
- Investment in Shares or Managed Funds: Some use equity to invest in the stock market, though this carries risks. It’s important to consult a financial advisor before pursuing this option.

Pros and Cons
Pros
- Access to Larger Loan Amounts: Equity-based loans offer larger amounts at lower interest rates, often more than personal loans.
- Potential Tax Deductions: For investment properties, some interest payments on equity loans may be tax-deductible.
- Property Value Growth: Using equity for renovations can increase your home’s market value, potentially adding to your equity.
Cons
- Risk of Property Loss: If you’re unable to make repayments, there’s a risk of losing your home, as it’s used as collateral.
- Increased Debt and Repayment Term: Borrowing against your equity increases your overall debt, which can lengthen your repayment timeline.
- Market Dependency: If property values decline, your equity may decrease, potentially leaving you owing more than your home’s worth.
Key Considerations Before Borrowing Against Your Home Equity
Using home equity requires careful planning. Here’s what to keep in mind:
- Affordability: Make sure you’re financially stable enough to manage increased repayments.
- Interest Rate Variability: For variable-rate loans, be prepared for potential interest rate hikes that could raise repayment costs.
- Emergency Funds: Avoid using all available equity to leave a financial cushion for emergencies.
- Loan Purpose Evidence: If borrowing large sums (typically $100,000 or more), be prepared to show proof of the intended use to lenders.
A financial advisor can help evaluate whether accessing home equity aligns with your long-term financial goals.
Conclusion
Home equity loans offer Australian homeowners significant financial flexibility, whether for investments, home improvements, or debt consolidation. Before applying, it’s essential to evaluate your financial position, compare lenders, and get expert advice. Contact Loan Nerds’ mortgage brokers today for personalized guidance to help you make the best choice for your financial goals!
Frequently Asked Questions
1. How much equity can I access?
Typically, lenders allow you to access up to 80% of your home’s value, minus any outstanding loan balance.
2. Can I use home equity for a second property?
Yes, equity can serve as a deposit on a new property, a common strategy for those looking to expand their property portfolio.
3. Are there different types of home equity loans?
Yes, options include top-up loans, lines of credit, and specific-purpose loans for renovations or investments.
Using your home’s equity can unlock new financial possibilities. With the right planning and guidance, you can take advantage of this asset to fund major life goals or increase your property’s value.

